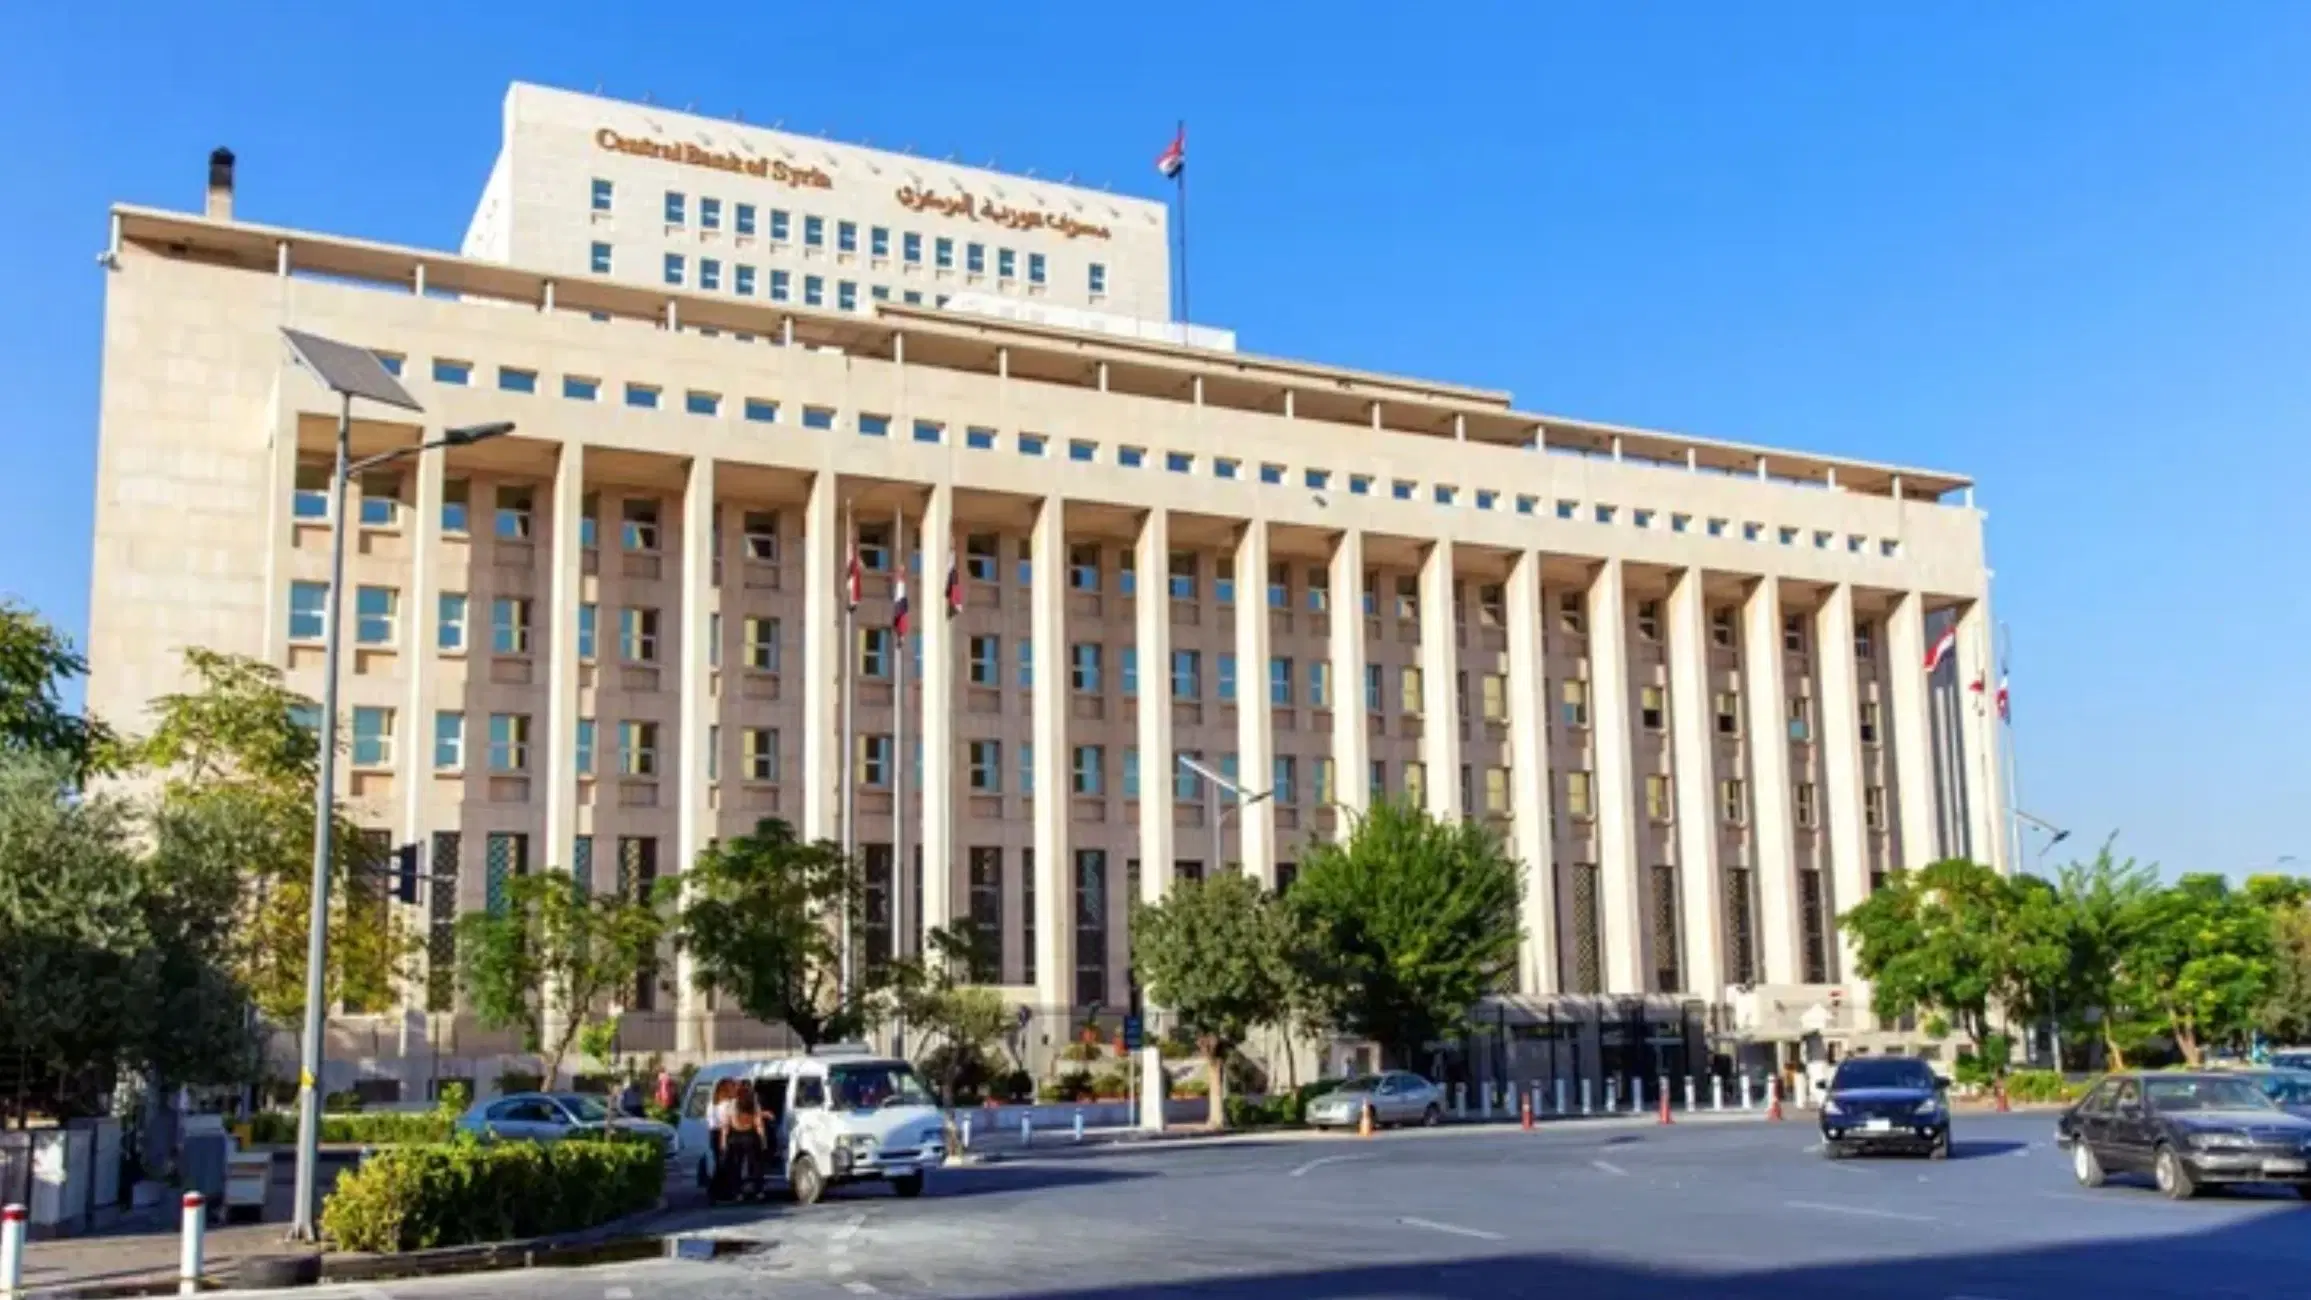
The Governor of the Central Bank of Syria, Mohammad Safwat Raslan, told (Petra) that banking cooperation between Syria and Jordan is ongoing, pointing out the importance of attracting more banks, investments, and expertise to the Syrian banking sector, consolidating relations with Jordanian, Arab, and foreign banks, benefiting from advanced banking experiences, and exchanging expertise in various fields.
Existing Jordanian banking investments in Syria include the Arab Bank-Syria, the International Bank for Trade and Finance, and the Bank of Jordan-Syria, reflecting the extension of banking relations between the two countries through investments and banking institutions operating in the Syrian market.
This presence forms a basis that can be built upon to expand banking cooperation, develop services provided to companies and individuals, and enhance the ability of financial institutions to keep pace with the needs of economic and commercial activity.
In turn, Jordanian banking institutions are exploring opportunities to enhance cooperation with the Syrian side and studying the potential for entering the market, as the Governor of the Central Bank of Syria held meetings in Amman with representatives of the Jordan Ahli Bank, Investbank, and the Commercial Bank, which addressed opening new channels, in addition to discussing the licensing and establishment of new banks in Syria.
These moves reflect an interest in expanding the base of banking institutions operating in the Syrian market, enhancing competition, and diversifying financial services, thereby supporting efforts to develop the banking sector and raise its efficiency.
Banking relations between Jordan and Syria acquire importance in light of the role of banks in financing trade and investment, facilitating payments and financial transfers, and providing the necessary services to companies and investors in both countries.
Developing correspondent banking channels and cross-border payments is considered a basic requirement to enhance the movement of trade exchange, as these channels allow for the execution of transactions and the settlement of financial liabilities with greater efficiency, and provide trade finance tools, including documentary credits, bank collections, and liquidity management.
In previous press statements, the Governor of the Central Bank of Jordan, Adel Sharkas, emphasized the importance of developing banking cooperation with Syria, including trade finance, payment and transfer channels, regulation, governance, risk management, and digital financial services.
The importance of cooperation in this field stands out with the growing need to provide a banking environment capable of meeting the requirements of companies and investors, and enhancing the efficiency of financial transactions between the two countries.
Achieving tangible progress in this path requires continuing to develop financial infrastructure, enhancing correspondent banking relationships, and adhering to compliance and regulatory requirements, including anti-money laundering and counter-terrorism financing procedures, and verifying customers and sources of funds.
The ability of banks to expand their activity is also linked to the availability of a clear regulatory environment, effective risk management procedures, and appropriate levels of confidence in the banking sector, which allows transforming existing cooperation into services and financing that support actual economic activity.
Reactivating banking relations with Syria provides opportunities for Jordanian financial institutions to expand their business in the areas of trade finance, corporate banking, remittances, and digital services, alongside studying opportunities to finance projects and economic activities.
Developing these services will support business movement between the two countries and contribute to meeting the needs of companies and investors, especially in sectors that require specialized financing and banking services.
However, benefiting from these opportunities requires a precise assessment of credit and operational risks, the availability of the legal and regulatory frameworks necessary to protect the rights of depositors and investors, as well as clarity of monetary and regulatory policies and the ability to manage liquidity.
Expanding banking activity also requires enhancing confidence in financial institutions, developing credit-granting tools, and directing resources toward productive activities and viable projects, rather than limiting the role of banks to executing payments and transfers.
Here, the role of banks in mobilizing savings and directing them toward investment stands out, thereby enhancing their capacity to support economic activity and provide the financial services needed by companies and individuals.
As for Jordan, the presence of existing banking investments and expertise in regional banking provides a basis for cooperation, while expansion decisions remain tied to studying market conditions, licensing and compliance requirements, economic feasibility, and risks associated with operating in the Syrian market.
In parallel with expanding cooperation with Arab banks, the Central Bank of Syria is studying the potential for employing financial technology and artificial intelligence in developing banking operations, improving their efficiency, and benefiting from regional and international experiences in this field.
Raslan stated that the bank is studying the experiences of neighboring countries and countries around the world in using artificial intelligence in banking operations, in preparation for benefiting from them in the central bank and transferring knowledge to banks operating in Syria.
He explained that these technologies can contribute to shortening time and improving the quality of operations, pointing out that there are discussions with specialized companies to examine the potential for employing modern technologies in banking work.
He stressed the necessity of providing clear regulatory frameworks to protect data and preserve banking secrecy, emphasizing the importance of coupling technological transformation with governance, risk management, and oversight.
Artificial intelligence applications, when employed according to appropriate controls, can contribute to accelerating transaction processing, improving customer services, enhancing the ability to analyze data and assess risks, as well as developing tools for detecting suspicious operations.
Benefiting from these technologies requires providing a secure digital infrastructure, qualifying human cadres, establishing clear data governance policies, and developing regulatory frameworks that ensure the protection of banking information and the reliability of operations.
Developing financial technology constitutes one of the paths that can support the modernization of the Syrian banking sector, provided that it is accompanied by the development of systems, procedures, and institutional capacities, thereby enhancing service efficiency and raising the level of security and transparency.
Banking movements between Jordan and Syria indicate the presence of opportunities to expand financial cooperation, in a manner consistent with the needs of trade and investment and the requirements of developing the Syrian banking sector.
Jordan possesses, through its banking institutions and existing investments, a base that can contribute to enhancing financial services between the two countries and providing the necessary expertise to develop the fields of financing, governance, risk management, and digital transformation.
In contrast, developing the Syrian banking sector requires increasing the capacity of financial institutions to provide financing, improving the efficiency of payments and transfers, expanding the scope of banking services, and enhancing confidence in the financial sector.