Middle East war and debt dominate IMF and World Bank meetings
Agencies6 min read
Share
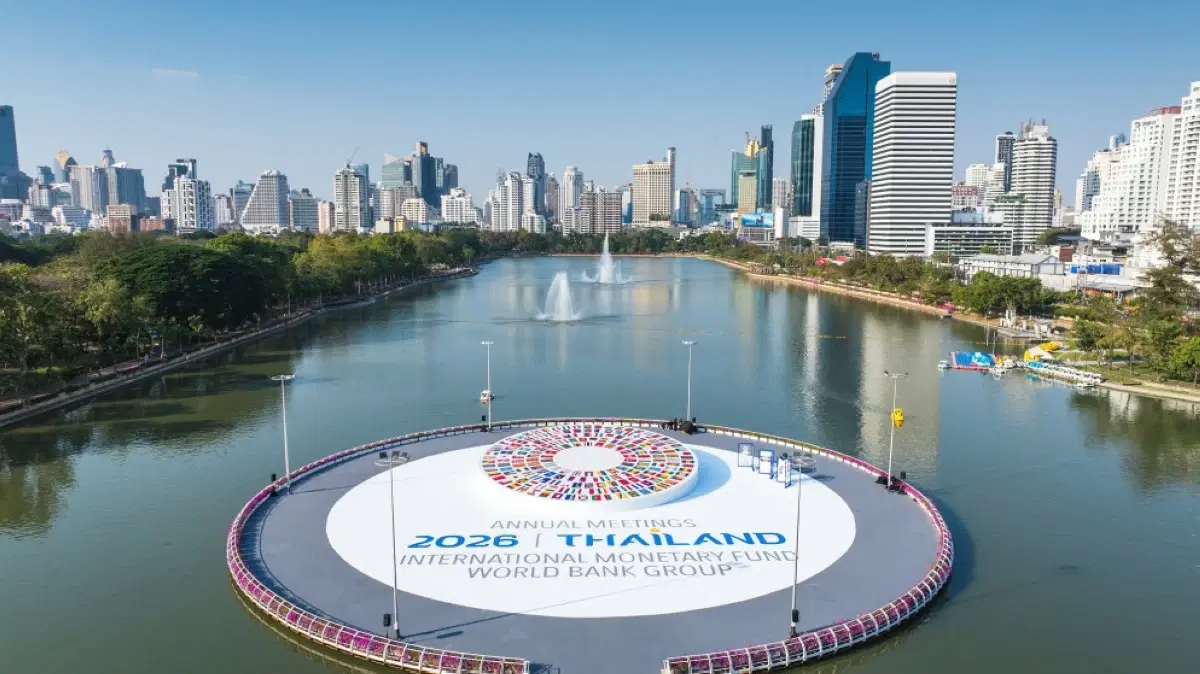
Financial officials from around the world are meeting in Thailand this week against the backdrop of a widening war in the Middle East, the largest-ever energy supply shock, and high interest rates—factors that together pose severe risks to global economic growth, which is already suffering from a slowdown.
The US-Israeli war against Iran, which has entered its eighth month, and the inflation and living hardships it has caused are expected to dominate the agenda and side discussions during the annual meetings of the International Monetary Fund and the World Bank, being held outside Washington for the first time in three years.
A notable absentee will be US Treasury Secretary Scott Bessent, who has dispatched two senior officials to represent him while he attends to some "domestic engagements," according to a US official.
Bessent's decision to skip this prominent gathering and a meeting of the G20, which the US is chairing this year, may spark discontent among his peers amid escalating tensions over the war in Iran, the Russia-Ukraine war, and the US decision to impose sanctions on the International Criminal Court.
World Bank President Ajay Banga told Reuters that while global growth held up better than expected when Iran closed the Strait of Hormuz, halting about 20% of global oil supplies, pressures are beginning to mount again.
He added that the sharp rise in diesel and fertilizer prices, coupled with an anticipated extreme El Niño phenomenon, which experts say could lead to 450,000 deaths from extreme heat, are all coinciding at the same time.
G7 countries agreed to release 100 million barrels of emergency diesel and crude oil reserves under pressure from US President Donald Trump, who is seeking to lower gasoline prices ahead of the November elections, in which his Republican Party could lose control of Congress.
Trump announced on Friday an agreement with Russia to pump more diesel into global markets, alongside a temporary waiver from US sanctions aimed at depriving Moscow of revenues to fund its war in Ukraine. The move was met with swift criticism from Ukrainian President Volodymyr Zelenskyy.
Since the outbreak of the war on February 28, more than a billion barrels of oil have been withdrawn, mostly from onshore commercial inventories, but energy executives say the volume of stored oil actually available to global markets is beginning to decline, increasing market fragility and boosting price pressures.
Banga said the World Bank does not currently plan to downgrade its global growth forecasts, but is monitoring developments closely.
He added, "The real issue is not El Niño alone, but the combination of factors together... What happens to fertilizer prices? What happens to energy costs? What happens to debts? The convergence of these factors is what poses its own challenges. And I think that will require all of us to be much more cautious in what we prepare for in the coming months."
- Rising Debt
IMF Managing Director Kristalina Georgieva issued a similar warning in her introductory remarks to the meetings, telling attendees, "Winter is coming."
The IMF ruled out any significant change to its global economic growth estimate of three percent for 2026, and may slightly upgrade its forecast for next year.
However, some countries will see downward revisions to their growth forecasts, including Ukraine, whose war has entered its fifth year against the Russian war, and Gulf countries hit by Iranian strikes and a sharp decline in energy exports.
Research published by the IMF on Tuesday showed that sharp spikes in food and energy prices have become an increasingly common source of crises that drive inflation expectations higher for longer periods, exacerbate poverty, and threaten economic stability.
The mounting burden of public debt is one of the biggest challenges facing policymakers, as it weakens economic growth and increases inflationary pressures. The IMF says public debt has reached its highest level since World War II and will exceed 100% of GDP before 2030.
Advanced economies, led by the United States, record the highest debt-to-GDP ratios, but emerging markets and low-income countries remain the most vulnerable amid a confluence of challenges, including capital outflows in search of higher yields in the US, the impacts of El Niño, and weak investment in artificial intelligence technologies, which have helped mitigate the effects of negative supply shocks in the US and other rich nations.
- Emerging Market Concerns
Developing countries are the most vulnerable due to high levels of public debt that will have to be renegotiated based on higher interest rates.
Interest payments already consume more than 10% of revenues in developing countries on average.
In the early stages of the COVID-19 crisis, G20 leaders announced a suspension of debt service payments for the poorest countries, but diplomats from G20 nations said enthusiasm for a similar step is practically non-existent currently, as high debt levels and political pressures pose greater obstacles this time.
Many low-income countries are concerned about new IMF recommendations on lending programs, which stipulate implementing fewer but deeper reforms as a condition for loan approval—a change many fear will lead to painful austerity measures.
Yolanda Fresnillo, who works on debt justice at the Eurodad network, said, "Countries are already cutting their spending due to high debt payments and because of IMF conditionality... And we fear that this conditionality review will make the situation worse."
She added that Kenya avoided debt restructuring by cutting public spending and trying to raise taxes, but these changes sparked widespread protests, particularly among young people.
She said the IMF risks losing its credibility unless it acknowledges the scale of the crisis facing many developing countries.
She explained, "As long as it continues to operate with its current governance structure, it will become less relevant and influential over time."
- Security and Economy
Flight paths to Bangkok often pass through the Middle East, posing direct security challenges for the more than 10,000 participants converging on the Thai capital, home to about nine million people, following the latest attacks on some Saudi airports.
Morocco hosted the last annual meetings of the IMF and the World Bank outside their headquarters.
Josh Lipsky, senior director of the Atlantic Council's GeoEconomics Center, said that after three years, the interconnectedness between national security and international finance has become clear, even though financial officials at the time ruled out Hamas's attack as an issue with economic dimensions.
Lipsky said, "Clearly, the global repercussions have been massive... And what we are currently seeing with Iran and the closure of the Strait of Hormuz is directly linked to what happened three years ago."
He added that policymakers need greater flexibility in dealing with geopolitical crises in an increasingly interconnected world, saying, "They need to act proactively and realize that they no longer live in the world they used to know."