Securities Commission launches "Environmental, Social, and Governance (ESG) Code of Practice"
To enhance investment appeal and consolidate the stability of the capital market
Amman11 min read
Share
The Securities Commission launched yesterday the "Environmental, Social, and Governance (ESG) Code", as part of enhancing the strategic position of the Jordanian capital market within the global financial landscape. Its implementation will become mandatory for the twenty companies making up the Amman Stock Exchange Index (ASE20) starting from the 2027 financial year, in accordance with the "apply and explain" principle, with the Commission keen to expand the implementation umbrella to include the rest of the listed companies at later stages.
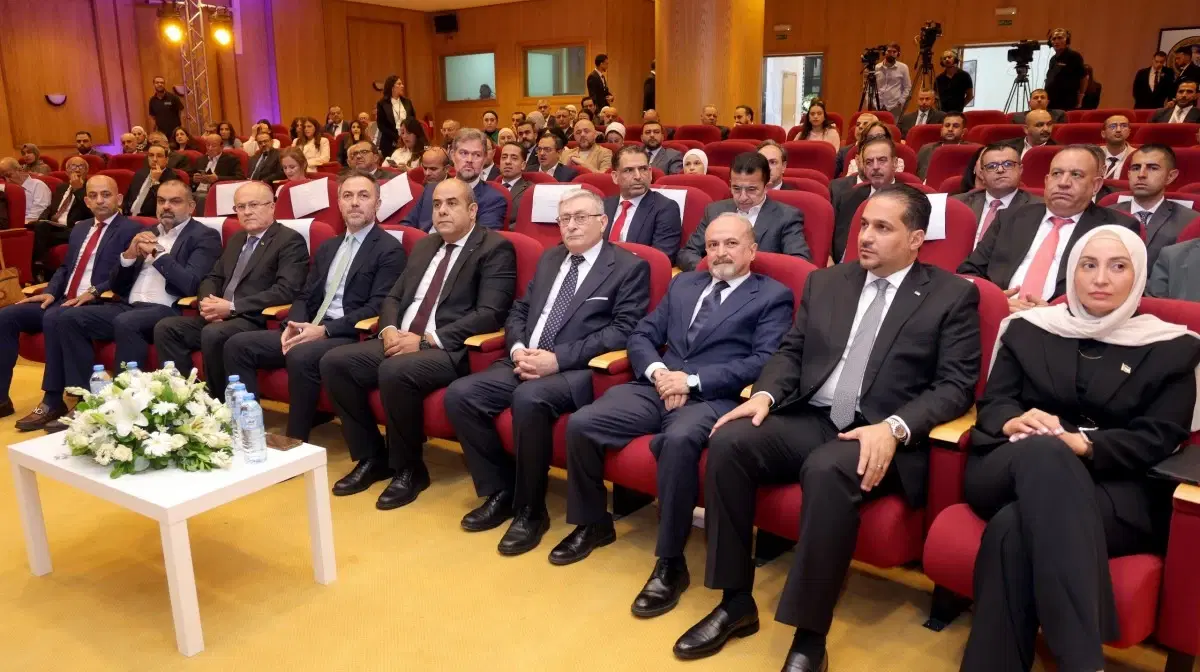
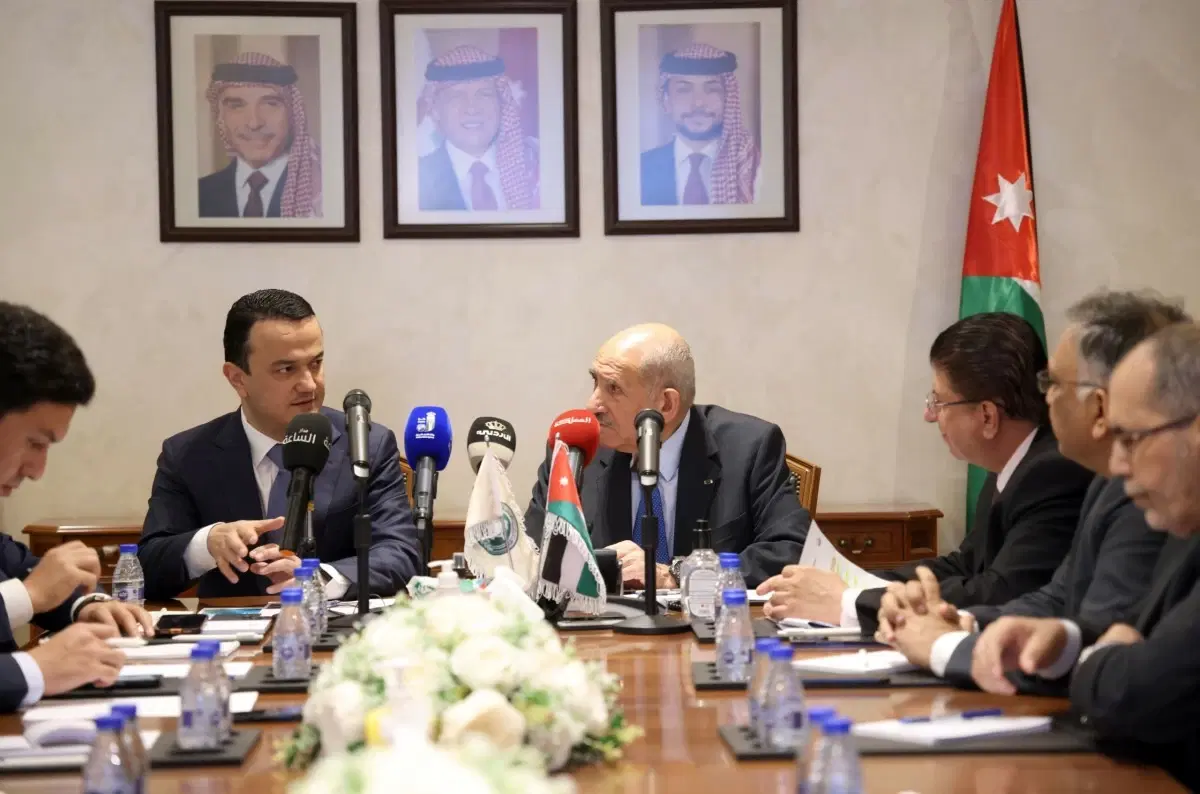
During a ceremony organized by the Commission at its headquarters, under the patronage of the Chairman of the Securities Commission, Mr. Emad Abu Hatlam, and in the presence of the representative of the Dutch Embassy in Amman, an elite group of officials from the Commission's partners among regulatory bodies, officials from the International Finance Corporation (IFC), participation from a representative of the International Sustainability Standards Board (ISSB), representatives of public shareholding companies and entities subject to the Commission's regulation, alongside members of the Board of Commissioners of the Commission, the Amman Stock Exchange, and the Securities Depository Center.
This code was developed within the framework of the Private Sector Development Program in the Middle East and North Africa (MENA) region, funded by the Kingdom of the Netherlands, in cooperation with the International Finance Corporation (IFC), capital market institutions, and relevant authorities.
This step comes in line with the Kingdom's national orientations towards achieving sustainable development and growth in green financing, establishing a comprehensive system aimed at improving governance, enhancing risk management, and raising the level of transparency and disclosure regarding sustainability opportunities and risks in Jordanian companies.
The Chairman of the Securities Commission, Mr. Emad Abu Hatlam, emphasized the pivotal importance of this transformation, stating: "Sustainability is no longer an option or a luxury; it has become an essential factor in competitiveness, building trust, and achieving long-term sustainable growth." He added: "This code sets a new standard for the Jordanian capital market in line with international sustainability standards, enhancing the confidence of local and international investors, and contributing to attracting qualitative and sustainable investments that support the stability of the national economy."
The Securities Commission called on the boards of directors of listed companies and their executive managements to adopt this strategic transformation, invest in it, and integrate sustainability principles into the core of decision-making processes, affirming the Commission's continued provision of the necessary support and the creation of a stimulating regulatory environment to ensure successful implementation.
For his part, the Country Manager of the International Finance Corporation in Jordan, Mr. Marcel Rashid, stated: "Attracting investments, reducing risks, and opening new growth horizons are at the core of every company's growth journey. This code aims to achieve precisely that; it enhances companies' commitment to sustainability, which increases their value, accelerates their expansion, and stimulates job creation, all of which remain at the core of the World Bank Group's mission."
The code aims to adopt international standards for sustainability disclosure issued by the International Sustainability Standards Board (ISSB), namely IFRS S1 regarding general requirements for disclosure of sustainability-related financial information, and IFRS S2 regarding climate-related disclosures, thereby raising the reliability of reports issued by Jordanian companies and making them internationally comparable.
It is worth noting that the prominent features of the code revolve around four main areas: governance of boards of directors and senior management, specialized committees, independent sustainability reports, and investor protection.
In the area of governance of boards of directors and senior management, the code establishes rules for the formation of boards of directors that require female representation, the presence of independent members constituting no less than one-third, alongside the availability of specialized expertise in sustainability and climate risks.
In the area of specialized committees, the code stipulates the formation of five main committees emanating from the board of directors, covering the areas of governance, sustainability, audit, risk, and nominations and remuneration.
In the area of independent sustainability reports, the code obligates companies to issue an independent annual sustainability report, affirming transparency and curbing the phenomenon of "greenwashing".
The code also includes provisions related to managing conflicts of interest, a code of conduct and professional ethics, the regulation of the internal control and internal and external audit environment, alongside compliance, transparency, and disclosure requirements, and the comprehensive sustainability framework.
During a panel discussion entitled "Developing Listed Companies' Practices to Achieve Sustainable Growth and Enhance Investment", the Director of the Corporate Planning and Development Department at the Amman Stock Exchange, Dr. Rasha Al-Diat, highlighted the most prominent technical and logistical challenges that listed companies, particularly ASE20 index companies, may face when turning the code's requirements and disclosures into a practical reality.
Al-Diat stated that the implementation of the Environmental, Social, and Governance Code represents an important step in developing corporate practices and enhancing their competitiveness, but its success requires dealing with a number of challenges related to the extent of companies' readiness and their ability to integrate sustainability principles into their business and decisions.
She explained that among the most prominent of these challenges is the shortage of expertise and specialized cadres in sustainability disclosure using the IFRS S1 and IFRS S2 standards, as their application requires skills that combine financial, environmental, social, governance, and risk management aspects, which are expertise that may not be sufficiently available.
She added that data collection and ensuring its quality represent a major challenge, especially since effective disclosure requires reliable, measurable, and comparable data, including, for example, energy and water consumption, emissions, waste management, worker health and safety, diversity, and others.
She pointed out that some companies may face initial costs associated with implementation, whether for developing data collection systems, training employees, utilizing specialized expertise, or developing systems.
Al-Diat emphasized that raising the readiness of boards of directors and executive managements also represents an important challenge; as the success of the code does not depend only on the existence of disclosure systems, but rather requires a true understanding by senior management of the importance of sustainability disclosure using IFRS standards, and its relationship to financial risks and opportunities and business sustainability, making capacity building and awareness raising an essential part of the implementation process.
She indicated that the success of the code should not be measured solely by the extent of companies' commitment to submitting disclosures, but rather by the extent to which sustainability becomes part of the way the company manages its business, by integrating it into strategy, governance, risk management, investment decisions, and operational processes.
In response to a question about whether the ESG code will remain merely a new regulatory requirement, or if it could constitute a turning point in the way Jordanian companies manage their business and create long-term value, Al-Diat said that the code may start as a regulatory requirement, but it should not end at the limits of compliance, as its true value lies in its ability to bring about a change in the way companies manage their business and make financial and strategic decisions.
She added that the sustainability report is no longer merely a disclosure topic, but has become a financial variable, and therefore the success of the report should not be measured solely by asking whether the company has prepared it, but by knowing whether ESG information has actually begun to influence the company's decisions.
She explained that ESG information can move from being mere data on energy consumption or emissions to an evaluation of risks, costs, and cash flows; as the process begins with operational data, then turns into risks, before translating these risks into a financial cost, leading to a value for the company that the investor can understand and evaluate.
She stressed the importance of the role of boards of directors and financial departments, explaining that sustainability should not remain a separate responsibility within the company, but must become part of the risk management framework, strategy, and financial decisions.
Al-Diat believes that sustainability reports can constitute a genuine turning point for Jordanian companies if they deal with them as a tool for improving performance, managing risks, and creating value, rather than just a new disclosure obligation.
Al-Diat summarized the objective of the code by saying: "The goal is not to move from having no ESG report to having an ESG report, or from one form to another, but rather to move from an ESG report to better decisions, lower risks, more efficient financing, and greater value for the company." The Director of the Corporate Planning and Development Department at the Amman Stock Exchange, Dr. Rasha Al-Diat, highlighted the most prominent technical and logistical challenges that listed companies, particularly ASE20 index companies, may face when turning the code's requirements and disclosures into a practical reality.
Al-Diat stated that the implementation of the Environmental, Social, and Governance Code represents an important step in developing corporate practices and enhancing their competitiveness, but its success requires dealing with a number of challenges related to the extent of companies' readiness and their ability to integrate sustainability principles into their business and decisions.
She explained that among the most prominent of these challenges is the shortage of expertise and specialized cadres in sustainability disclosure using the IFRS S1 and IFRS S2 standards, as their application requires skills that combine financial, environmental, social, governance, and risk management aspects, which are expertise that may not be sufficiently available.
She added that data collection and ensuring its quality represent a major challenge, especially since effective disclosure requires reliable, measurable, and comparable data, including, for example, energy and water consumption, emissions, waste management, worker health and safety, diversity, and others.
It pointed out that some companies may face initial costs associated with implementation, whether for developing data collection systems, training employees, utilizing specialized expertise, or developing systems.
Aldiyat emphasized that raising the preparedness of boards of directors and executive managements also represents a significant challenge, as the success of the code does not rely solely on having disclosure systems, but rather requires a genuine understanding by senior management of the importance of sustainability disclosure using IFRS standards, and its relationship to financial risks, opportunities, and business sustainability, making capacity building and raising awareness an essential part of the implementation process.
She indicated that the success of the code should not be measured solely by the extent of companies' commitment to submitting disclosures, but rather by the extent to which sustainability becomes part of how a company manages its business, by integrating it into strategy, governance, risk management, investment decisions, and operational processes.
In response to a question about whether the ESG code will remain merely a new regulatory requirement or can constitute a turning point in how Jordanian companies manage their business and create long-term value, Aldiyat said that the code may begin as a regulatory requirement, but it should not end at the boundaries of compliance, as its true value lies in its ability to bring about a change in the way companies manage their business and make financial and strategic decisions.
She added that the sustainability report is no longer merely a subject for disclosure, but has become a financial variable, and therefore the success of the report should not be measured only by asking whether the company has prepared it, but by knowing whether ESG information has actually begun to influence the company's decisions.
She explained that ESG information can transition from mere data on energy consumption or emissions into an assessment of risks, costs, and cash flows; the process begins with operational data, then turns into risks, before these risks are translated into a financial cost, ultimately leading to a company value that the investor can understand and evaluate.
She emphasized the importance of the role of boards of directors and financial managements, explaining that sustainability should not remain a separate responsibility within the company, but must become part of the risk management, strategy, and financial decisions framework.
Aldiyat considered that sustainability reports can constitute a real turning point for Jordanian companies if they treat them as a tool for improving performance, managing risks, and creating value, rather than merely a new disclosure obligation.
Aldiyat summarized the goal of the code by saying, "The goal is not to move from having no ESG report to having an ESG report, or from one form to another, but rather to move from an ESG report to better decisions, lower risks, more efficient financing, and greater value for the company."